Constructed Portfolio Worksheet
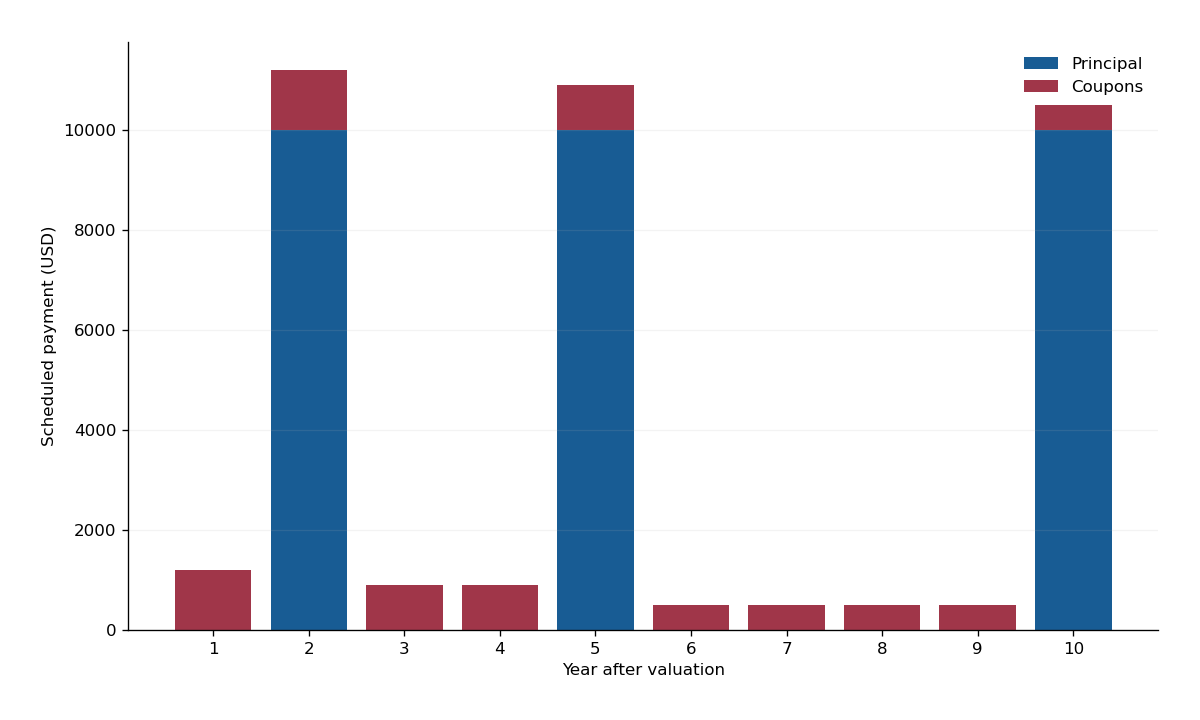
Bond cash-flow ladder
Scheduled payments and immediate repricing under explicit rung-level assumptions.
Present value$29,587.96
Total face$30,000.00
DV01 (USD / bp)$14.05
Modified duration4.7488
Repriced value$28,699.63
Value change$-888.32
Exact price change-3.0023%
Rung-level valuation
| Rung | Present value | Modified duration | DV01 (USD / bp) | Shifted yield | Repriced value | Value change |
|---|---|---|---|---|---|---|
| Two-year rung | $9,809.61 | 1.9173 | $1.88 | 5.00% | $9,623.80 | $-185.81 |
| Five-year rung | $9,778.34 | 4.4747 | $4.38 | 5.25% | $9,456.51 | $-321.83 |
| Ten-year rung | $10,000.00 | 7.7946 | $7.79 | 5.50% | $9,619.32 | $-380.68 |
Scheduled annual payments
| Year | Coupons (USD) | Principal (USD) | Total payments (USD) |
|---|---|---|---|
| 1 | $1,200.00 | $0.00 | $1,200.00 |
| 2 | $1,200.00 | $10,000.00 | $11,200.00 |
| 3 | $900.00 | $0.00 | $900.00 |
| 4 | $900.00 | $0.00 | $900.00 |
| 5 | $900.00 | $10,000.00 | $10,900.00 |
| 6 | $500.00 | $0.00 | $500.00 |
| 7 | $500.00 | $0.00 | $500.00 |
| 8 | $500.00 | $0.00 | $500.00 |
| 9 | $500.00 | $0.00 | $500.00 |
| 10 | $500.00 | $10,000.00 | $10,500.00 |
All rungs use the regular coupon-date convention and one selected coupon frequency. Each yield is a flat discounting assumption for that rung, not an interpolated market curve. Payments assume no default and no calls. Coupons and principal are not reinvested; the schedule is not ending wealth or realized return. Inflation, costs, taxes and currency conversion are absent.
Yield changes are separate from payments
The stress column changes each rung's present value immediately. It does not change that fixed-coupon instrument's scheduled cash receipts.
Three-rung worked exampleInput files stay local
CSV files are read in your browser page. No file is sent to a pricing service, saved to an account or treated as a verified security record.
Methods and exclusions