Cash Flows & Pricing
Trace regular bond cash flows, yields, compounding and the boundaries of a price calculation.
Cash flows first.
Conventions alongside every result.
Bond price, duration, convexity and exact yield-shock repricing.
Regular noncallable fixed-coupon bullet bond, valued on a coupon date before the next full coupon period; nominal annual yield compounded at coupon frequency; no accrued interest, default, optionality, tax, costs or reinvestment.
Hypothetical USD amounts. Values stay in this page; no input upload or persistent storage. Yield shock changes yield immediately, with no elapsed time.
Calculation conventionsDV01 is a positive first-order sensitivity magnitude, not an exact one-basis-point loss. Approximation error uses percentage points.
| Period | Years | Coupon | Principal | Payment | Present value |
|---|---|---|---|---|---|
| 1 | 0.5 | $20.00 | $0.00 | $20.00 | $19.51 |
| 2 | 1 | $20.00 | $0.00 | $20.00 | $19.04 |
| 3 | 1.5 | $20.00 | $0.00 | $20.00 | $18.57 |
| 4 | 2 | $20.00 | $0.00 | $20.00 | $18.12 |
| 5 | 2.5 | $20.00 | $0.00 | $20.00 | $17.68 |
| 6 | 3 | $20.00 | $0.00 | $20.00 | $17.25 |
| 7 | 3.5 | $20.00 | $0.00 | $20.00 | $16.83 |
| 8 | 4 | $20.00 | $0.00 | $20.00 | $16.41 |
| 9 | 4.5 | $20.00 | $0.00 | $20.00 | $16.01 |
| 10 | 5 | $20.00 | $1000.00 | $1020.00 | $796.82 |
Trace regular bond cash flows, yields, compounding and the boundaries of a price calculation.
Compare exact repricing with duration, convexity and position-sized sensitivity.
Distinguish rate conventions, curve construction and parallel or maturity-specific shocks.
Separate spread sensitivity from default, optionality, inflation and trading frictions.
Inspect scheduled payments, reinvestment assumptions, liability questions and validation records.
Separate scheduled coupons, maturing principal and current value across up to twelve constructed rungs. Assign each rung its own yield and scenario change.
Open the cash-flow ladderA duration estimate is local. A wide shock tests how much the linear or quadratic approximation departs from discounting every unchanged payment again.
Inspect the five-year example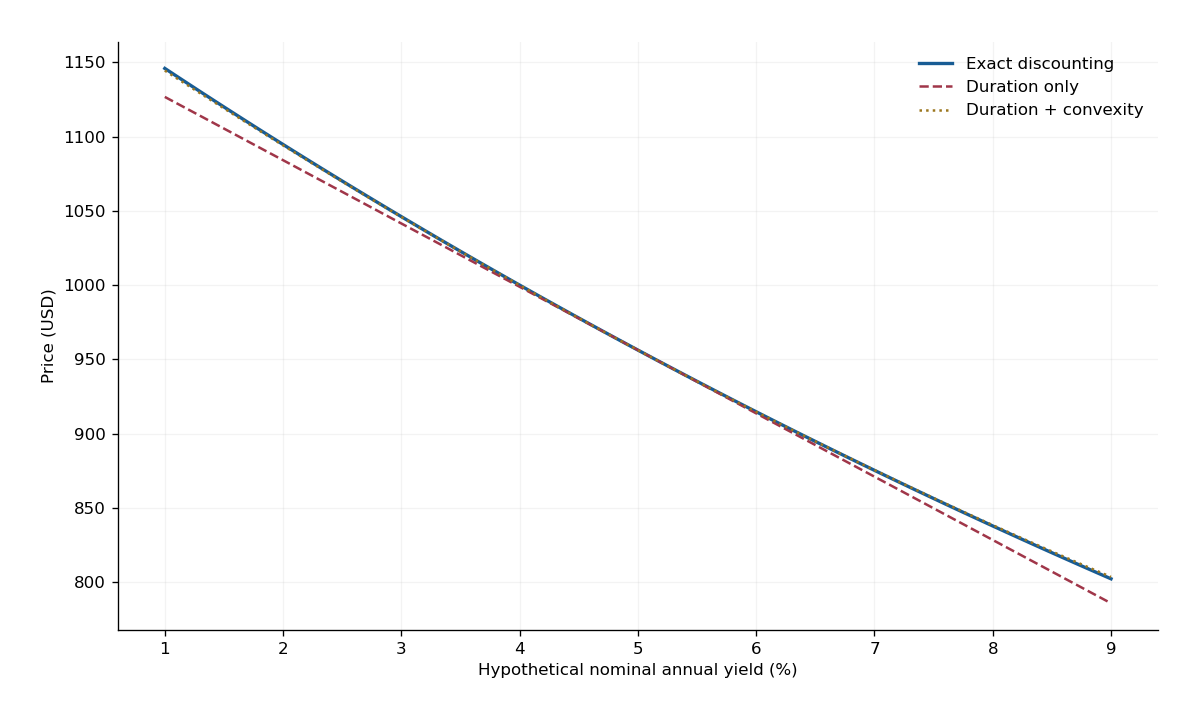
Reconcile a $956.24 starting value, a $914.70 repriced value and two duration approximations using an explicit coupon schedule.
Trace the exampleTrace a single future payment, a 10-year Macaulay duration and the limits of a local yield-shock estimate.
Trace the exampleUse exact repricing to isolate a hypothetical yield change while keeping spread, default risk and market execution separate.
Trace the exampleReconcile $30,000 of face value, $7,600 of scheduled coupons and maturity-specific yield shocks without assuming reinvestment.
Trace the exampleDarren O'Neill's published competition record and quantitative preparation provide founder context. A fixed-income use case still needs its own instrument coverage, model documentation and dated sample.
Review the provider profile